LATEST COMMENTARY
FIVE THINGS TO KNOW
MCT READER PULSE · MCT-PULSE-2026-017
MCT READER SURVEY
Gaano ka nagtitiwala na tama ang ginagawa ng Kongreso sa budget ng bayan?
This is an informal survey of people who choose to participate. It is not a scientific or nationally representative sample.
ABOUT THE MANAGER’S CHECKS AND THE QUESTIONS OVER SARA DUTERTE’S SALN
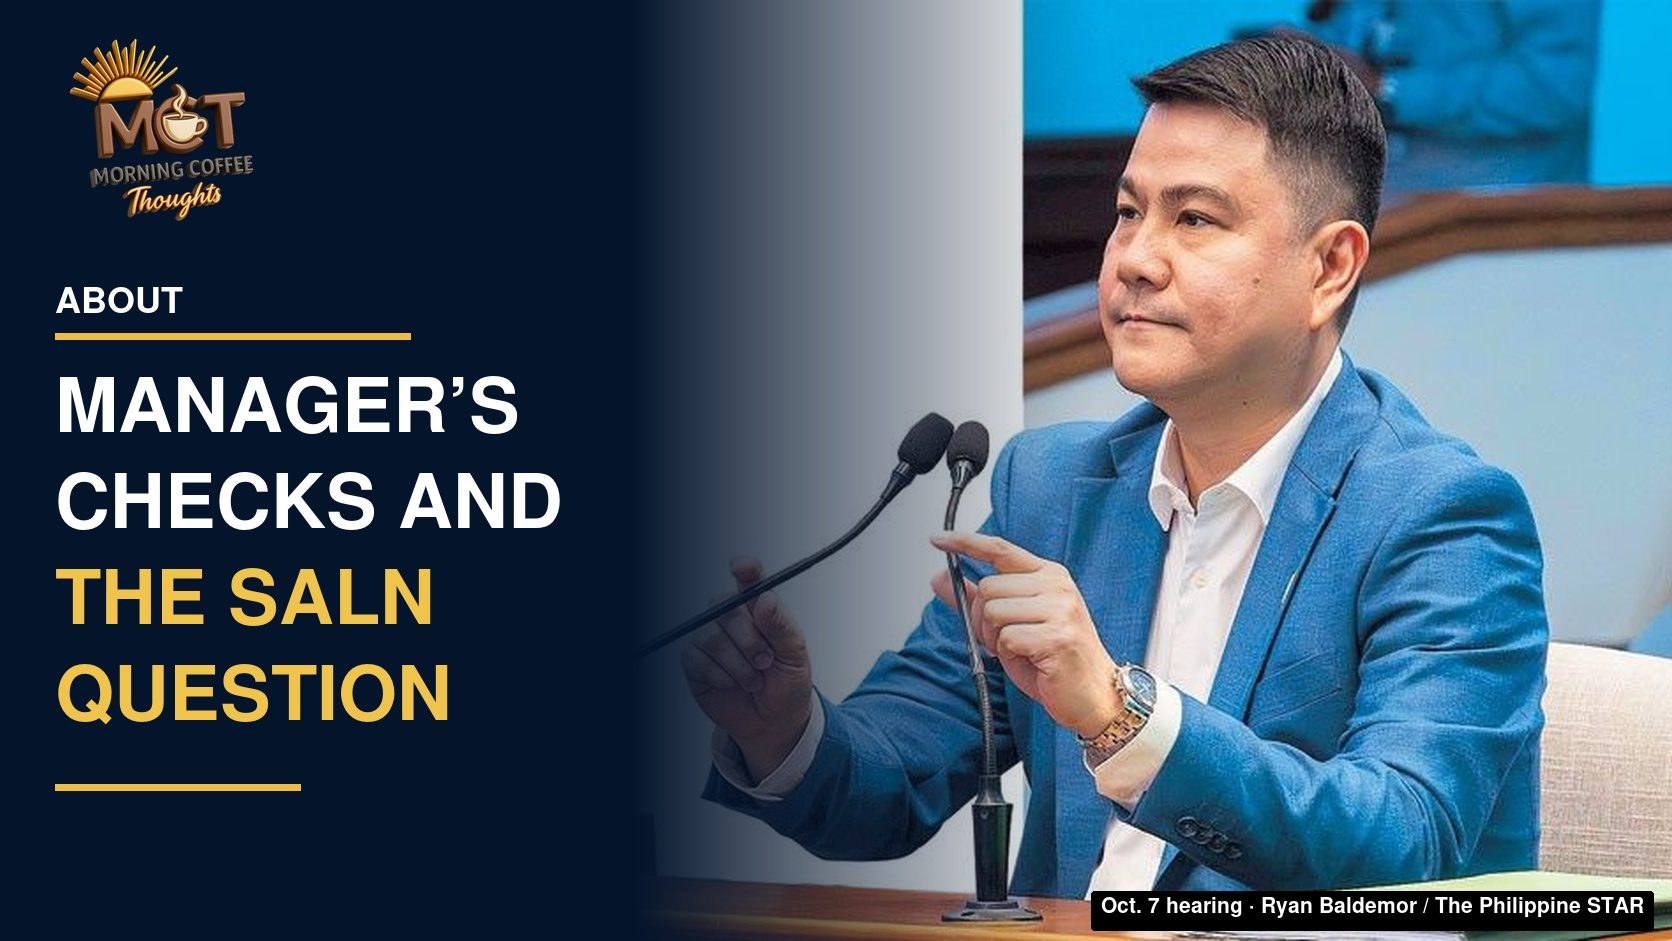
A bank balance can fall even when the value represented by the money has not disappeared. That distinction sits behind the prosecution’s questions about manager’s checks in Sara Duterte’s impeachment trial. To understand the October 7 testimony, we need to follow the instrument, the person entitled to its value and the declaration of assets for the relevant year.
1
A MANAGER’S CHECK IS THE BANK’S OWN PROMISE TO PAY
A manager’s check is issued by a bank against itself. The purchaser supplies the funds, commonly through a debit to an account, and the bank issues a check payable to the named recipient. Supreme Court decisions describe it as a primary obligation of the issuing bank. Its issuance does not automatically mean the amount has been deposited into the payee’s account.
WHAT TO WATCH
This is an ordinary banking instrument with legitimate uses. The issue in the trial is how particular checks were used and accounted for. A check’s purchase, delivery, presentation, cancellation and eventual payment are different events; the records must establish which occurred.
2
THE PROSECUTION IS TRACING MONEY THROUGH DIFFERENT FORMS
GMA’s account of Galvez’s testimony traces a joint peso time deposit opened in January 2010 with a principal of ₱40.65 million. Renewals and interest brought it to about ₱41.7 million. The witness described records of a manager’s-check purchase in March 2011 and an unutilized check later that year. Prosecutor James Alih said the panel intended to establish a continuing pattern involving that money, another ₱55 million and later insurance purchases.
WHAT TO WATCH
These amounts should not simply be added each time they appear in a new instrument. If the same funds move between a deposit, a check and another asset, repeated entries can describe successive stages of one money trail. The dates and identities of the instruments are needed to determine whether amounts are separate or overlap.
3
A LOWER YEAR-END BANK BALANCE DOES NOT ANSWER THE WHOLE SALN QUESTION
Galvez explained that money allocated to a manager’s check would not appear in the purchaser’s account balance while it remained in the bank’s settlement account. The prosecution argues that this could conceal assets at year-end. That is the allegation to test against the records, rather than a conclusion supplied by the banking mechanism alone.
WHAT TO WATCH
Republic Act No. 6713 requires disclosure beyond a bank balance, including personal property, investments, cash and other assets. Annual SALNs refer to the position as of December 31 of the preceding year. The relevant inquiry is what asset or financial interest the official held on that date, its proper disclosure and whether it appeared in the declaration. Moving value into another form does not, by itself, explain whether the declaration was complete.
4
THE ACCOUNT SIGNATURES AND TRANSACTION SIGNATURES ARE DIFFERENT EVIDENCE
According to GMA’s report, presiding officer Francis Escudero confirmed Sara’s signature on account-opening and KYC documents, including an update dated June 13, 2023. He also confirmed that her signature did not appear on the transactions examined for the account ending in 9539. Defense counsel Michael Poa said she did not recall the account and had not participated in those transactions.
WHAT TO WATCH
Both parts belong in the explanation. A signature on an identity or account record establishes a different fact from a signature authorizing a particular payment. The absence of the latter does not erase the former; the presence of the former does not alone establish that she instructed every transaction. Knowledge, ownership, control and disclosure each need evidence.
5
THE MONEY TRAIL STILL HAS TO MEET THE DECLARATION
The useful comparison is between the dated bank records, the checks’ beneficiaries and disposition, the relevant SALNs and the explanations offered by each side. A financial instrument may account for a change in a bank balance while leaving unanswered who retained an interest in its value. That is why following only the year-end balance can leave a reader with an incomplete picture.
WHAT TO WATCH
The Senate must decide what the evidence proves under the impeachment charge. Buying a manager’s check is not itself a finding of concealment, and a defense statement is not itself a complete account of the money.
BOTTOM LINE
The significance of yesterday’s hearing is that it gives the court specific records and disputed explanations to compare.
GOOGLE PREFERRED SOURCES
FOLLOW MCT ON GOOGLE
Google’s Preferred Sources feature lets you choose publications you want Google to prioritize for you. Select “Add to Preferred Sources” to make MCT easier to find in Top Stories and other eligible Google results. This does not subscribe you to email.
SUPPORT MCT
HELP KEEP INDEPENDENT POLITICAL WRITING GOING.
Morning Coffee Thoughts is reader-supported. Contributions help pay for research tools, hosting, and the work required to verify and explain each development.